By Sir Hannibal
Turning 40 has a way of making money feel different.
In your 20s, retirement can seem like something happening to another version of you. In your 30s, you’re often juggling housing, children, debt, career changes and everyday life. Then 40 arrives and a question gets harder to ignore:
How much should I actually have saved by now?
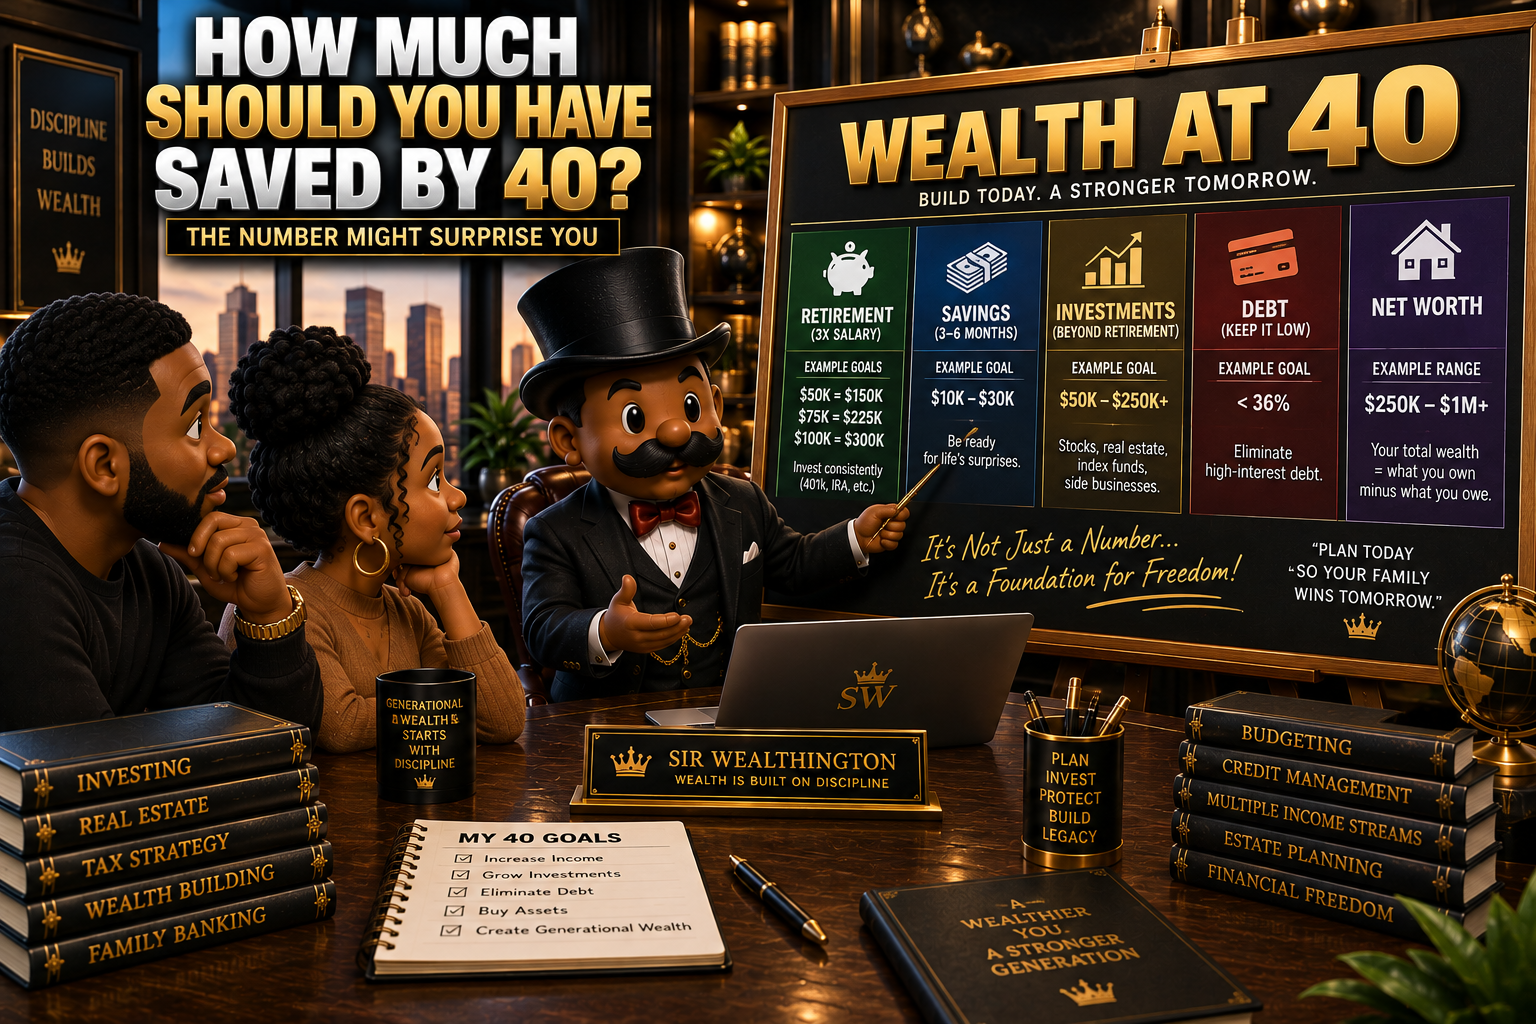
One widely used benchmark says you should aim to have roughly three times your annual salary saved for retirement by age 40. Fidelity currently uses that guideline, along with 1x salary by 30, 6x by 50 and 10x by 67.
That means someone earning:
| Annual Income | 3x Benchmark at 40 |
|---|---|
| $50,000 | $150,000 |
| $75,000 | $225,000 |
| $100,000 | $300,000 |
| $150,000 | $450,000 |
Seeing those numbers can be encouraging if you’re ahead.
If you’re nowhere close, they can be terrifying.
But here’s what matters: the benchmark is a planning tool, not a financial report card.
Your real financial position at 40 requires looking at much more than one number.
The famous “3x your salary” rule needs some context
Suppose you’re 40 and earn $80,000.
Using the 3x guideline, your retirement savings target would be approximately $240,000.
That doesn’t mean you should necessarily have $240,000 sitting in a savings account.
We’re talking primarily about money accumulated toward retirement through accounts such as a:
401(k).
403(b).
Traditional IRA.
Roth IRA.
Other long-term retirement investments.
Fidelity’s benchmark assumes, among other things, saving about 15% of income annually beginning at age 25, retiring around age 67 and investing using an age-appropriate allocation.
Change those assumptions and your target can change.
Someone planning to retire at 55 may need considerably more.
Someone expecting a pension has a different financial picture.
Someone who didn’t begin earning substantial income until 35 shouldn’t necessarily compare themselves with someone who began a high-paying career at 22.
Personal finance is personal.
Use benchmarks to determine what might need attention—not to determine your self-worth.
Retirement savings aren’t the same thing as your total financial life
Here’s another reason the question gets confusing.
Someone says:
“I have $100,000 saved.”
What does that actually mean?
Is it $100,000 in a 401(k)?
$30,000 in cash and $70,000 invested?
Does it include home equity?
Does it include a business?
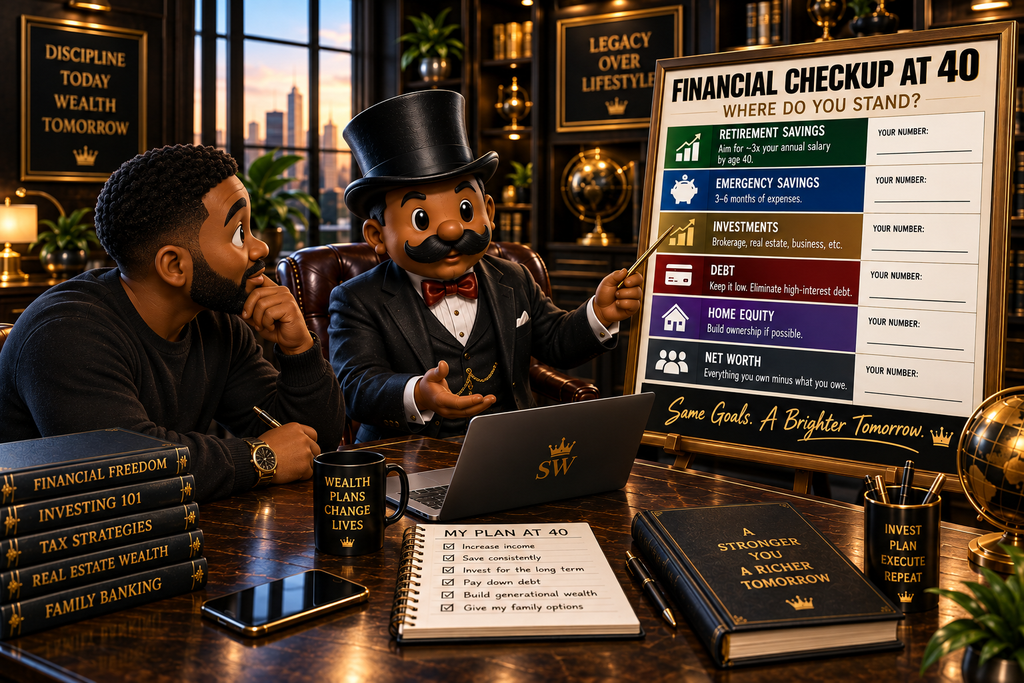
When discussing how much you should have saved by 40, separate your money into categories.
You might have:
Emergency savings for unexpected expenses.
Retirement investments intended for your later years.
Taxable investments for other long-term goals.
Home equity representing part of your net worth.
Business ownership that may have value.
Cash for near-term goals such as a home purchase.
All of those can contribute to your financial strength, but they don’t perform the same job.
A house worth $500,000 doesn’t necessarily help you pay a $2,000 emergency tomorrow.
And $30,000 sitting in checking isn’t the same as $30,000 invested toward retirement.
At 40, knowing what you own and what each dollar is supposed to do becomes increasingly important.
Your net worth may tell you something your savings balance doesn’t
This is where I’d want a 40-year-old to calculate another number:
Net worth.
The formula is simple:
Everything you own − everything you owe = net worth.
Imagine two 40-year-olds each have $100,000 in retirement accounts.
Person A also has:
$80,000 in home equity
$20,000 in other investments
$15,000 in cash
$10,000 of consumer debt
Person B has:
$5,000 in cash
No home equity
$50,000 in consumer debt
Their retirement balances are identical.
Their overall financial positions clearly aren’t.
This is why I wouldn’t obsess over one age-based savings number.
At 40, look at the whole board.
Being behind at 40 is serious—but it isn’t a reason to give up
Let’s say you’re 40 years old and have only $25,000 invested for retirement.
You look at the 3x benchmark and realize you’re substantially behind.
What now?
The worst response would be deciding you’ve already failed, so there’s no point trying.
You potentially still have more than two decades before a traditional retirement age.
The better question becomes:
How much can I change between 40 and 50?
Imagine starting with $25,000 and investing $750 per month for the next 10 years.
Assuming a hypothetical 7% annual return, you’d have roughly $176,000 by age 50.
Increase that contribution to $1,000 per month under the same hypothetical assumptions and you’d reach roughly $219,000.
Those aren’t guaranteed outcomes. Markets fluctuate, investment returns vary, and fees and taxes can affect actual results.
But the example demonstrates something powerful.
Being behind today doesn’t mean you’ll remain in the same position.
Your savings rate from this point forward matters enormously.
Your 40s may be some of your most important wealth-building years
There’s a reason I wouldn’t treat turning 40 like a financial funeral.
For many people, their 40s can coincide with higher earnings than they had earlier in their careers.
Some expenses may eventually change.
Debt can be eliminated.
Careers can advance.
Businesses can grow.
And there’s still meaningful time for long-term investments to potentially compound.
Fidelity currently suggests working toward saving at least 15% of pretax income for retirement, including employer contributions, although the right percentage depends on your situation.
If 15% isn’t realistic today, that doesn’t mean you do nothing.
Maybe you’re contributing 6%.
Can you reach 7%?
Then 8%?
When you receive a raise, could half of that increase go toward investing?
Small increases can become meaningful when repeated for years.
Don’t leave free employer money sitting on the table
If your employer offers a 401(k) match, understand exactly how it works.
Suppose your employer matches contributions up to a certain percentage of your salary.
If you’re eligible but don’t contribute enough to receive the full match, you’re potentially giving up part of your compensation package.
At 40, I’d want to know:
What’s my employer match?
Am I receiving all of it?
How much am I contributing annually?
What am I actually invested in?
What fees am I paying?
You don’t need to become obsessed with your retirement account every day.
But you should understand what your money is doing.
Your Roth IRA can become another piece of the system
A workplace retirement plan doesn’t have to be your only retirement account.
Depending on eligibility and your situation, an IRA may provide another tax-advantaged place to save.
For 2026, the IRA contribution limit is $7,500 for people under 50. The IRS also sets income limits affecting Roth IRA contributions and the deductibility of some traditional IRA contributions.
The 2026 employee contribution limit for most 401(k) plans is $24,500.
You don’t have to max out these accounts to benefit from them.
The point is to understand the tools available to you.
Someone contributing $300 a month consistently is building more than someone waiting until they can afford $1,000 a month and never starting.
At 40, debt deserves a harder look
Saving and investing are only one side of wealth building.
What are you carrying on the other side?
Credit cards.
Personal loans.
Car payments.
Student loans.
Mortgage debt.
Not all debt deserves identical treatment, but high-interest consumer debt can compete directly with your ability to build wealth.
Imagine investing $500 every month while simultaneously carrying a credit-card balance charging more than 20% interest.
You need to look at the entire equation.
At 40, I’d want a plan for eliminating expensive debt while continuing to build appropriate savings and investments.
The objective isn’t simply:
“How much money do I have?”
It’s:
“How strong is my entire financial position?”
If you’re doing well, don’t use 40 as permission to coast
There’s another side to this conversation.
Maybe you’re 40 and already have $300,000 invested.
Great.
But don’t automatically assume the job is finished.
Your target depends on the life you’re trying to finance.
Do you want to retire at 67?
At 60?
At 55?
Do you want your mortgage eliminated before retirement?
Do you want to leave assets to your children?
Help grandchildren attend college?
Own investment property?
Build a family business?
Retirement is only one destination for wealth.
At Black Dollar & Culture, we’re also interested in what happens after a family accumulates assets.
Who owns them?
How are they protected?
How are children educated about them?
How does one generation help the next without destroying accountability?
That’s when personal finance starts becoming family wealth.
Your number at 40 matters less than what happens at 41
If you’re 40 and behind, acknowledge it.
Don’t hide from the numbers.
Pull up the 401(k).
Check the IRA.
Write down the debts.
Calculate your net worth.
Look at your monthly spending.
Then build the plan.
If you’re earning $75,000 and have nowhere near the roughly $225,000 suggested by the 3x benchmark, you haven’t received a financial death sentence.
You’ve received information.
Now decide what to do with it.
Increase contributions.
Capture your employer match.
Attack expensive debt.
Avoid unnecessary lifestyle inflation.
Build emergency savings.
Invest for the long term according to your goals and risk tolerance.
Increase your income when possible.
Then review the numbers again.
Because the most dangerous financial position at 40 isn’t necessarily being behind.
It’s being behind and refusing to look.
Forty can still give you something incredibly valuable:
time to change the direction of the next 20 or 30 years.
Build More Than a Retirement Account
Saving for retirement is about taking care of your future. Building family wealth asks an additional question:
What happens to everything you’re building after you?
Family Bank Starter System
Get the Family Bank Starter System
Family Wealth Trust Blueprint / ILIT Guide
Get the Family Wealth Trust Blueprint
SEO BLOCK
SEO TITLE: How Much Should You Have Saved by 40? The Number Might Surprise You
META DESCRIPTION: How much should you have saved by 40? See the 3x salary benchmark, examples at different incomes and what to do if you’re behind.
URL SLUG: how-much-should-you-have-saved-by-40
FOCUS KEYPHRASE: how much should you have saved by 40
CATEGORY: Money Tips
ESTIMATED READING TIME: 6 minutes