By Sir Hannibal
Most advice about saving money sounds simple.
Stop eating out.
Cancel subscriptions.
Make coffee at home.
Those things can help, but if you’re trying to save money fast, cutting a few small expenses isn’t enough. You need a temporary financial strategy that creates a meaningful gap between what comes in and what goes out.
Think of it as a savings sprint.
For the next 30, 60 or 90 days, your money has a specific mission.
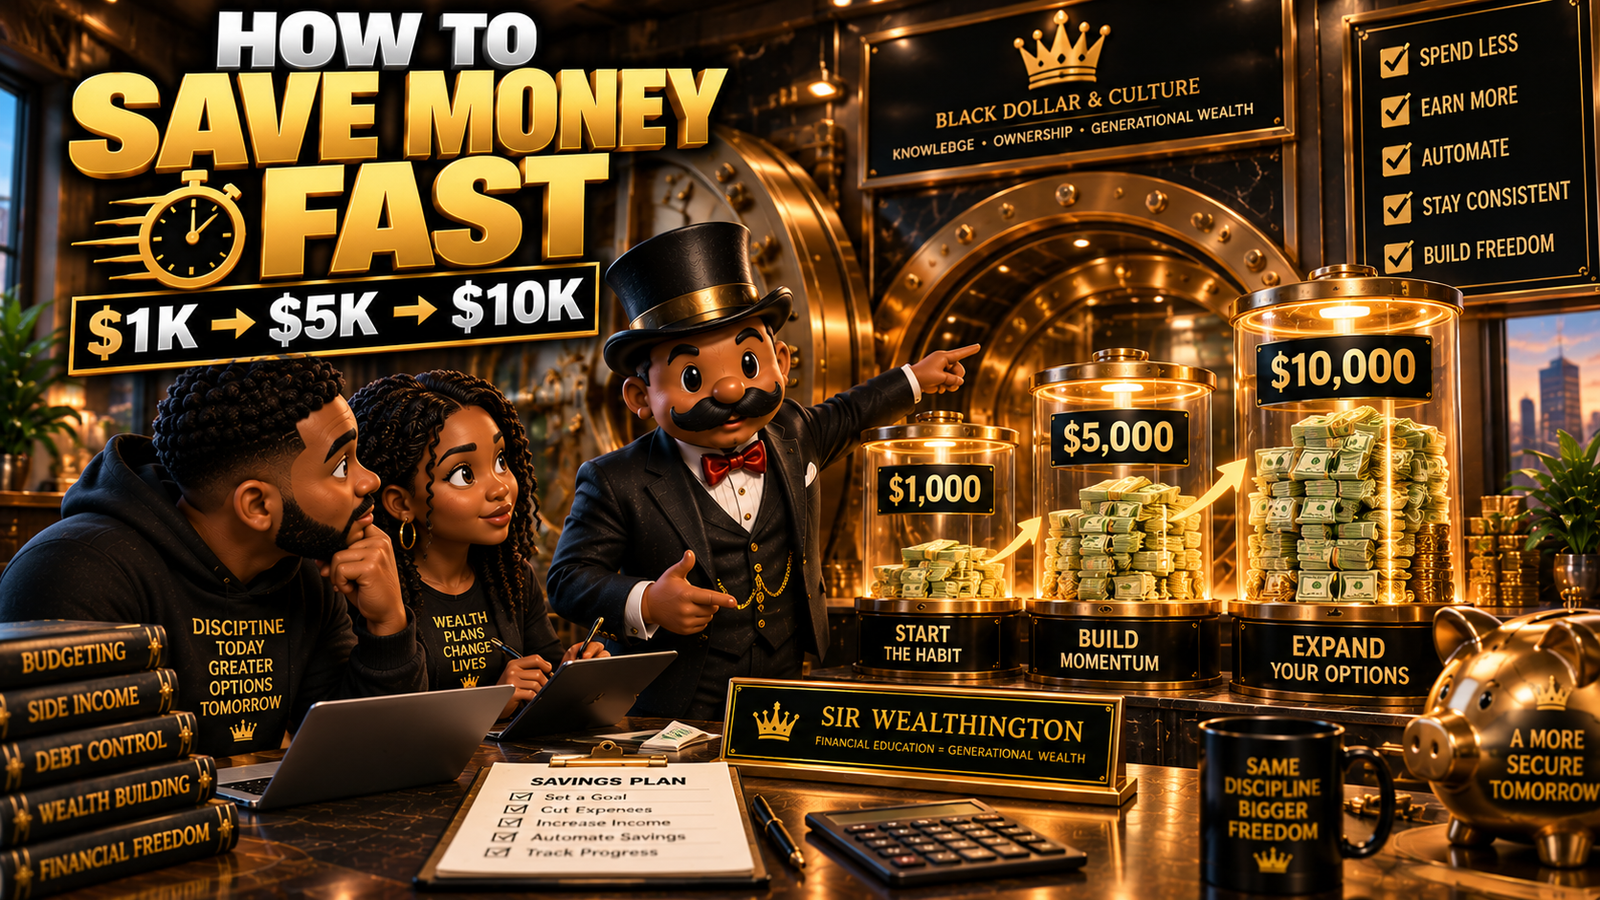
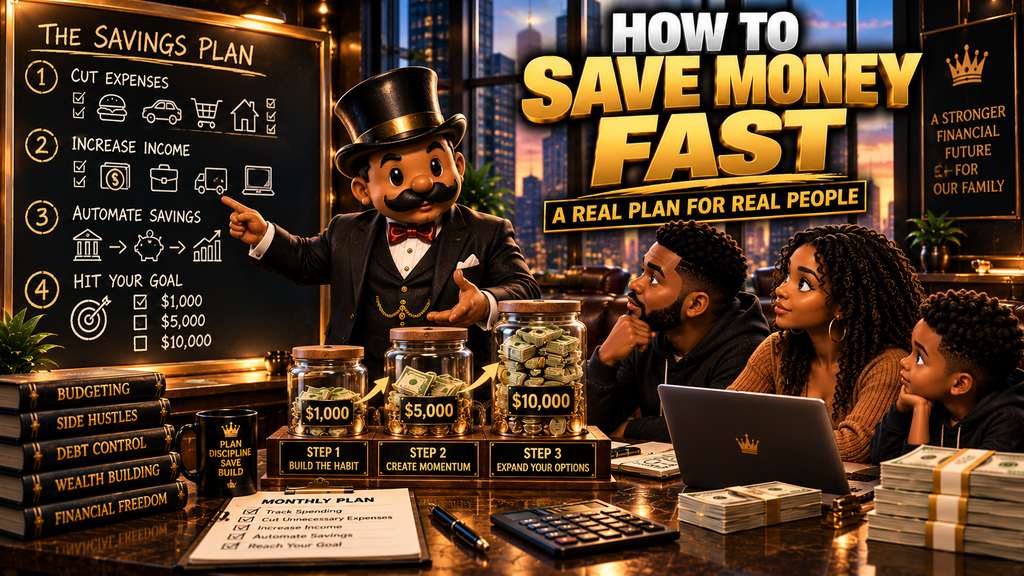
Maybe you need your first $1,000 emergency fund.
Maybe you’re trying to reach $5,000 so one unexpected expense doesn’t destroy your finances.
Or maybe you’ve decided that this is finally the year you build your first $10,000.
Whatever the number is, the process starts the same way:
Stop saving whatever happens to be left over. Start deciding how much will be left over.
Give Your Savings a Number and a Deadline
“I need to save more money” isn’t a plan.
“I want $5,000 saved by March 31” is.
Once you have a number and deadline, you can work backward.
Suppose you want to save $3,000 in 90 days.
That’s:
$1,000 per month
About $231 per week
Or roughly $33 per day
Suddenly, the goal becomes measurable.
Now you can ask a much better question:
Where am I going to find $1,000 each month?
That’s where the real work begins.
Find the Big Money Before Chasing the Small Money
If you’re trying to save $5,000 quickly, spending 20 minutes searching for a $3 coupon probably isn’t your highest-value move.
Look at your largest expenses first.
Housing.
Transportation.
Food.
Insurance.
Debt payments.
Childcare.
Subscriptions and recurring bills.
Then look for expenses that have quietly become normal.
Maybe you’re paying $250 a month for cable, streaming services and subscriptions.
Maybe food delivery is costing $400.
Maybe you have an expensive phone plan.
Maybe you’re paying for memberships you barely use.
Maybe shopping has become a weekly habit instead of an occasional purchase.
Pull your last 60–90 days of bank and credit-card statements and look at what actually happened.
Don’t build a savings plan around what you think you spend.
Build it around what your statements prove you spend.
Try a 30-Day Financial Lockdown
If you genuinely need to save money fast, temporarily change the rules.
For 30 days, separate spending into two categories:
Necessary and optional.
Rent?
Necessary.
Electricity?
Necessary.
Groceries?
Necessary.
Another pair of shoes?
Optional.
Random Amazon purchase?
Optional.
Friday night takeout when there’s food at home?
Optional.
This doesn’t mean you can never enjoy money again.
It’s a sprint.
You might decide that for the next 30 days there will be no unnecessary clothing purchases, no impulse Amazon orders, limited restaurant spending and no major entertainment purchases.
If that frees up $600, you’ve accomplished more in one month than saving $5 here and $8 there without a larger strategy.
Don’t Just Cut Expenses—Go Find Money
This is where most savings advice falls short.
There’s a limit to how much you can cut.
Your income has much more room to grow.
Suppose you’ve already cut $400 per month from your spending.
Good.
Now find another $600 through income.
Overtime.
Extra shifts.
Freelance work.
Weekend work.
Selling unused items.
Temporary gig work.
A small service business.
Seasonal work.
Monetizing a skill you already have.
Now you’ve created:
$400 from cutting expenses + $600 from additional income = $1,000 per month.
That’s $3,000 in 90 days.
This is why I prefer attacking savings goals from both sides.
Spend less temporarily. Earn more aggressively.
Sell the Stuff That’s Sitting Around Your House
Look around your home.
There’s a good chance some of your savings account is currently sitting in your garage, closet or spare bedroom.
Old electronics.
Furniture.
Shoes.
Tools.
Collectibles.
Exercise equipment.
Baby items your children have outgrown.
Gaming systems.
Clothes.
Appliances.
You don’t need to sell everything you own.
But if you can turn ten unused items averaging $50 each into cash, that’s:
$500.
If your first goal is $1,000, you’re already halfway there.
Make Saving Automatic on Payday
The FDIC recommends automatic transfers as one way to build savings because money can be moved into savings before you have an opportunity to spend it.
That’s powerful because most people do the opposite.
Their system is:
Income → Bills → Spending → Hopefully save something
Flip it:
Income → Savings → Bills → Spending
If you’re paid every two weeks and your target is $5,000 over approximately six months, you might automate roughly $385 from each of 13 paychecks.
You can adjust that number for your actual pay schedule and cash flow.
The important part is that savings becomes a planned transaction, not a monthly accident.
Keep Emergency Savings Separate
Your savings account shouldn’t feel like an extension of your checking account.
If you constantly see an extra $3,000 sitting beside your spending money, it becomes easy to think:
“I’ll borrow $200 from myself and replace it next paycheck.”
Then $200 becomes $500.
And the money never gets replaced.
Consider keeping emergency savings in a separate FDIC-insured savings account. The standard FDIC deposit-insurance amount is $250,000 per depositor, per insured bank, for each account ownership category.
A competitive high-yield savings account can also allow emergency money to earn interest while remaining accessible, although rates can change.
The purpose isn’t to chase every tenth of a percentage point.
It’s to make your cash work while keeping it available when a genuine emergency occurs.
Give Yourself Three Targets
Trying to save six months of expenses when you currently have $87 can feel overwhelming.
Break the journey down.
Target One: $1,000
This is your first layer of protection.
A tire blows.
The refrigerator breaks.
You have an unexpected bill.
Instead of immediately reaching for a credit card, you have cash available.
Target Two: $5,000
Now you’re creating breathing room.
Depending on your household expenses, $5,000 could absorb a much larger emergency or cover part of a period without income.
Target Three: $10,000
This is where something interesting begins to happen psychologically.
You’re no longer proving that you can save a few hundred dollars.
You’ve demonstrated that you can accumulate capital.
And once you’ve learned how to accumulate $10,000, the next question becomes:
What should this money eventually do for me?
Don’t Invest Money You May Need Next Month
Saving and investing serve different purposes.
Money for next month’s rent shouldn’t be riding the stock market.
Neither should money you know you’ll need shortly for an emergency expense.
The SEC emphasizes that investment choices should account for your time horizon and risk tolerance. Money needed for shorter-term goals generally requires different treatment from money being invested for decades.
Your emergency savings has a job.
Its job isn’t necessarily to generate the highest possible return.
Its job is to be there.
Once you have adequate emergency reserves, then you can think more aggressively about investing additional money for long-term wealth.
Watch What Happens When Your Income Increases
Raises can disappear remarkably quickly.
You earn an additional $400 a month.
Then the car gets upgraded.
The restaurants get better.
Subscriptions multiply.
Shopping increases.
Six months later, you make more money but still feel broke.
When your income increases, capture part of the increase before your lifestyle absorbs it.
If your take-home pay increases $500 per month, perhaps you immediately redirect $250 toward savings or investing.
You still get to enjoy some of the raise.
But your wealth also rises.
The Fastest Savings Plan Is the One You Can Actually Repeat
Suppose you run a 90-day savings sprint and accumulate $4,000.
Great.
Don’t immediately return to the exact financial behavior you had before.
Maybe you were saving $1,000 a month during the sprint.
You might decide that $1,000 isn’t sustainable forever.
Fine.
Could you continue saving $500?
That’s still $6,000 per year before interest.
Over five years, that’s $30,000 in contributions.
The sprint taught you something important:
You discovered how much financial capacity existed inside your household.
Don’t give all of it back.
Saving Money Is Really About Buying Options
The biggest benefit of saving $10,000 isn’t looking at $10,000 in a bank account.
It’s what that money changes.
A car repair doesn’t automatically become debt.
A job loss doesn’t immediately become panic.
You can walk away from certain bad situations.
You can potentially take advantage of an opportunity.
You can begin investing from a stronger foundation.
You can help your family without immediately borrowing money yourself.
Eventually, savings can become capital.
Capital can buy assets.
Assets can produce income.
Income can purchase more assets.
That’s when saving stops being merely about surviving emergencies and starts becoming part of a larger wealth-building system.
Your first $1,000 matters.
Your first $5,000 matters.
Your first $10,000 matters.
But the most important thing you’re building isn’t the account balance.
You’re building the financial discipline that made the balance possible.
Turn Your Savings Into a Family Wealth System
Once your household learns how to accumulate money consistently, the next question is how your family can organize and deploy capital together.
Family Bank Starter System
Get the Family Bank Starter System
And as your family accumulates investments, insurance and other assets:
Family Wealth Trust Blueprint / ILIT Guide