By Sir Hannibal | Black Dollar & Culture
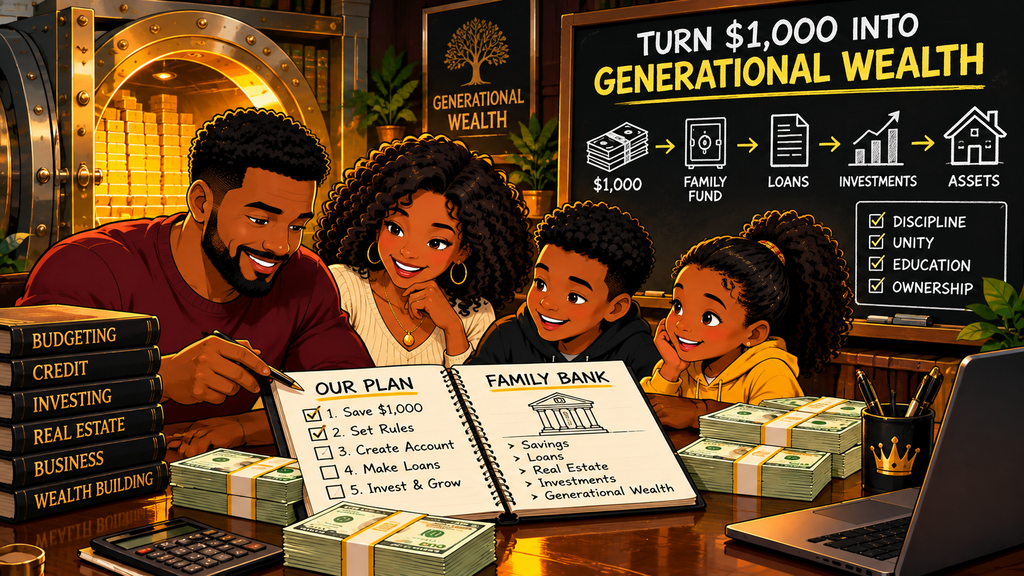
What if your family stopped waiting for someone to become wealthy and started building wealth together?
Imagine five family members contributing $200 each. That’s $1,000 in collective capital.
It won’t buy an apartment building or fund a major business overnight. But it can become the foundation of something powerful: a family-controlled financial system.
A family bank isn’t necessarily a physical bank. In this context, it’s a structured arrangement where relatives pool money, establish rules, support shared financial goals, and eventually build assets together.
The goal is simple:
Turn individual contributions into collective financial power.
And you don’t need to be rich to begin.
Why Start a Family Bank?
Many families approach money individually.
One person struggles with an emergency. Another wants to start a business. Someone else needs help with a down payment.
Everybody is trying to solve their financial problems alone.
A family bank creates an opportunity to work together instead.
With the right structure, your family can establish an emergency reserve, provide carefully controlled financial assistance, save toward investments, and teach younger generations how money works.
But the most important ingredient isn’t money.
It’s trust, accountability, and written rules.
Without those three things, even a family fund with $100,000 can fall apart.
How to Get Your First $1,000
You don’t need one wealthy relative to finance everything.
Start with a small group of committed participants.
Build Your First $1,000
Contributing family members
5
Starting fund goal
$1,000
Each member contributes
$200.00
Total family capital
$1,000
Illustrative equal contributions. Families can also agree to different amounts and document how that affects ownership or participation.
The amount matters less than establishing a contribution system everyone can realistically maintain.
A family member contributing $25 consistently may be more valuable to the long-term system than someone promising $1,000 and never following through.
Put the Rules in Writing Before Collecting Money
This is where many informal family money arrangements go wrong.
Someone contributes money believing it’s an investment. Another person thinks it’s a donation. A third person expects to borrow whenever they need help.
Those misunderstandings can destroy relationships.
Before collecting funds, create a written family agreement that answers several important questions:
- Who can join, and how much must each person contribute?
- Are contributions gifts, deposits, loans, or ownership investments?
- Who controls the account, and who can authorize withdrawals?
- Can members request loans? If so, what are the repayment terms?
- What happens if someone stops contributing or wants to leave?
- How will the family resolve disputes?
Have a qualified attorney review the arrangement before treating contributions as investments or issuing loans. The legal structure matters.
Where Should the First $1,000 Go?
Your first goal shouldn’t be to turn $1,000 into $10,000 overnight.
It should be to protect the money and establish a reliable system.
For a newly organized family fund, consider keeping the initial capital in an appropriately titled, insured deposit account while the family develops its agreement.
Avoid putting the money into one relative’s personal account without clear documentation.
If the group eventually forms an LLC, trust, or another legal entity, the appropriate account ownership and tax treatment may change.
And don’t call the arrangement a licensed bank or offer deposit-taking services to the public. A private family savings or lending arrangement is not the same as a regulated bank.
Turn $1,000 Into a Family Financial System
Once your family has established its rules and secured the money, focus on growing the fund through consistent contributions.
For example, imagine five relatives each contribute $50 every month after the initial $1,000.
Family Bank Growth Calculator
Family members
5
Monthly amount per person
$50
Contribution period
1 year3 years5 years10 years
Projected family fund balance
$16,000
Starting with $1,000 · No withdrawals, interest, fees or investment returns assumed
Family fund
$0$4K$8K$12K$16KStartYear 1Year 2Year 3Year 4Year 5
Illustrative contribution-only projection; not an investment return forecast.
The family doesn’t have to take unnecessary investment risks to make meaningful progress. Regular contributions alone can create a pool of capital.
When Should Your Family Start Lending Money?
Not immediately.
A $1,000 fund is fragile. One unpaid $800 loan could nearly wipe it out.
First, establish a reserve, prove that members can contribute consistently, and decide how much money—if any—can safely be lent.
If your family later approves a loan, document the amount, purpose, repayment schedule, interest terms if applicable, and what happens if the borrower cannot repay. The Consumer Financial Protection Bureau specifically recommends discussing expectations and putting family lending arrangements in writing.
Consumer Financial Protection Bureau
Depending on your structure and location, lending can raise tax, licensing and consumer-protection questions. Obtain professional advice before starting a recurring lending program.
Your First 90 Days
Days 1–30
Organize the familyInvite 3–5 committed relativesAgree on the purpose of the fundDiscuss contributions and ownershipDraft the family agreement
Days 31–60
Build the foundationGet legal and tax guidance where neededOpen an appropriately titled accountCollect the initial $1,000Create a shared contribution ledger
Days 61–90
Establish disciplineBegin monthly contributionsHold the first financial reviewSet reserve and withdrawal rulesChoose a realistic one-year goal
The Bigger Picture: From Family Savings to Family Ownership
The first $1,000 isn’t the destination.
It’s the beginning of a new financial habit.
Over time, a well-managed family fund might support financial education, carefully documented assistance, or a shared investment project after the family establishes the appropriate legal structure.
Imagine relatives gathering once a month to review their financial progress, teach their children about money, and discuss opportunities to build assets together.
That’s how a family bank can become more than a savings account.
It can become a family institution.
Wealth doesn’t always begin with having a lot of money. Sometimes it begins with getting the people around you organized.
And $1,000 can be enough to begin that conversation.
Start Building Your Family Bank
Family Bank Starter System: A resource for developing your family’s contribution rules, financial organization, and long-term wealth-building approach.Get the Family Bank Starter System
Family Wealth Trust Blueprint: Explore how estate planning and life insurance trusts may fit into a family’s longer-term wealth protection strategy.Explore the Family Wealth Trust Blueprint
This article is educational, not individualized legal, tax or financial advice. A family fund is not an FDIC-chartered or licensed bank; insurance coverage depends on the actual deposit account ownership and institution.